Your existing Paid Family and Medical Leave [PFML] program may qualify for federal tax credits — even when no employee takes leave.
On July 4, 2025, new legislation made IRC Section 45S tax credits permanent and expanded their applicability and potential value for employers from 2026. If you previously reviewed the credit and ruled it out, it’s time to look again.
_______________________
Credits of Up to 25%—Now Extended to Premiums
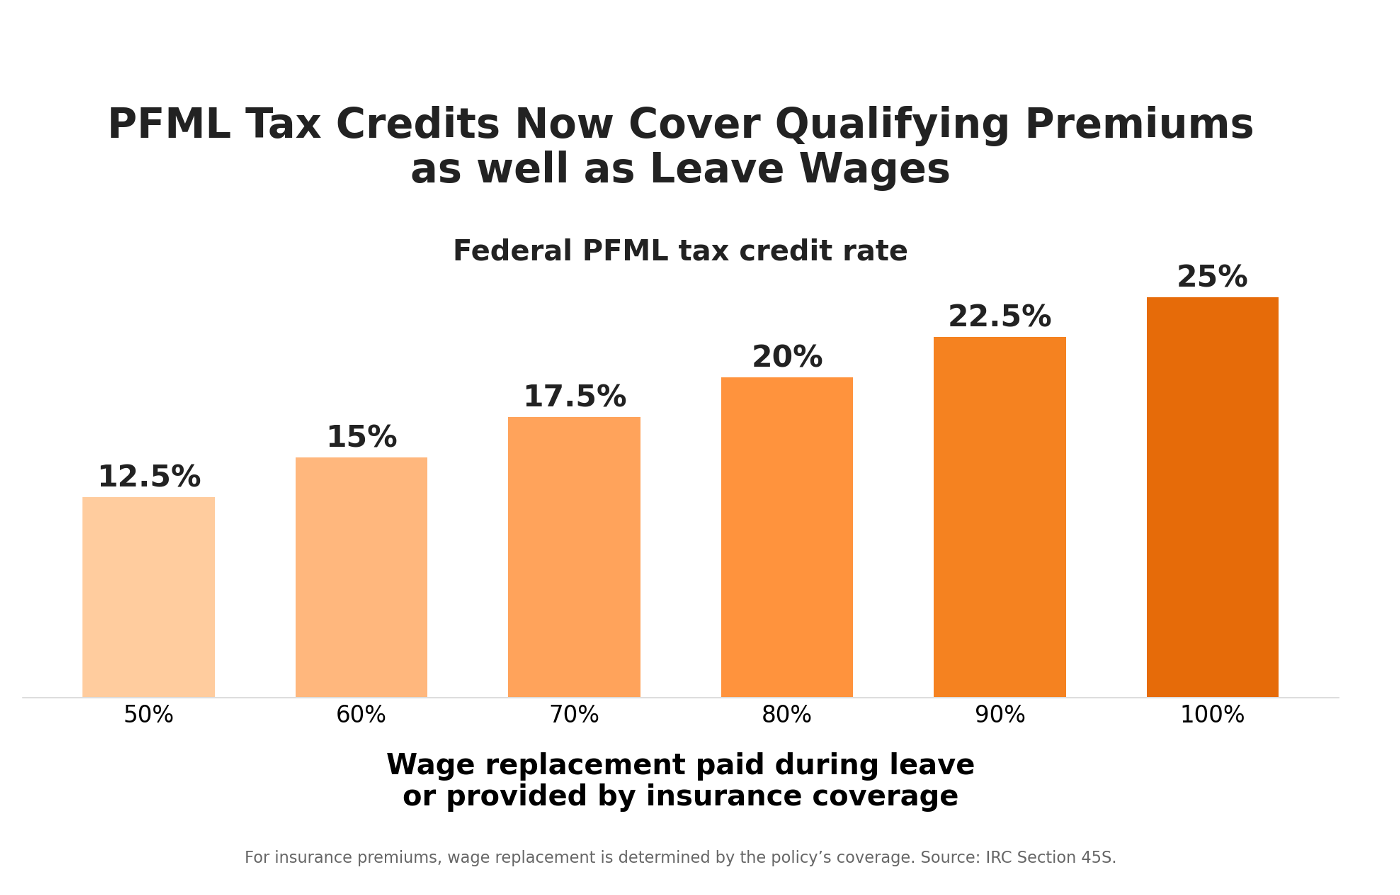
Paid Family and Medical Leave plays an increasingly important role for attracting and retaining talent. Section 45S is designed to help fund that investment through federal tax credits of up to 25% of qualifying leave wages or insurance premiums.
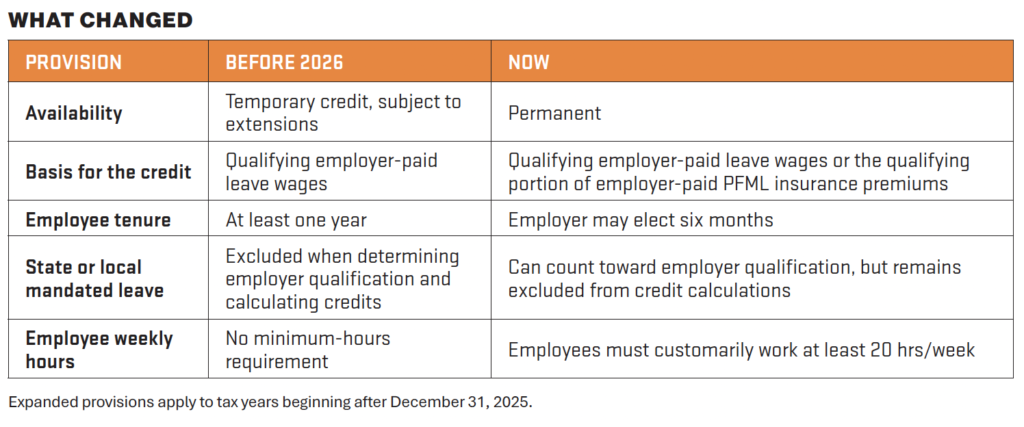
The premium option is particularly significant. Employers can now claim credits on qualifying PFML insurance premiums — even when qualifying employees take no leave during the year. Other changes allow employees to qualify sooner and state-mandated leave to count toward employer qualification.
For employers, this creates an opportunity to reduce net PFML costs and help fund stronger leave programs. Parental leave, short-term disability, and family caregiving deserve a fresh review — not only as a strategic benefits investment, but as sources of potential credit value.
_______________________
Section 45S at a Glance
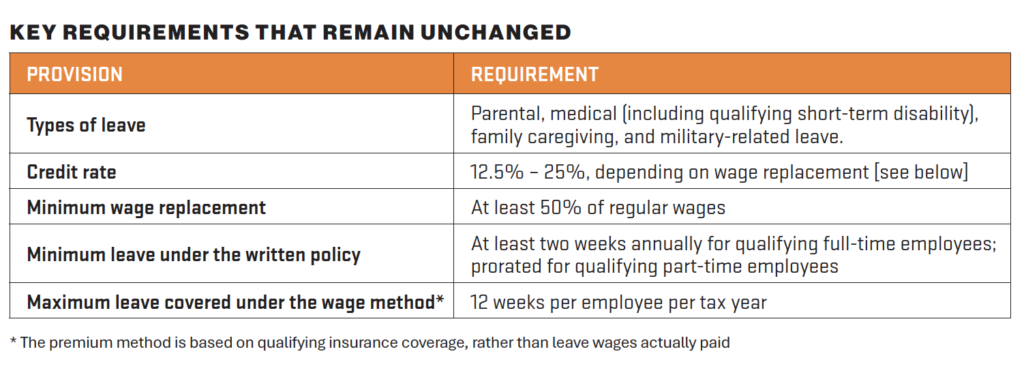
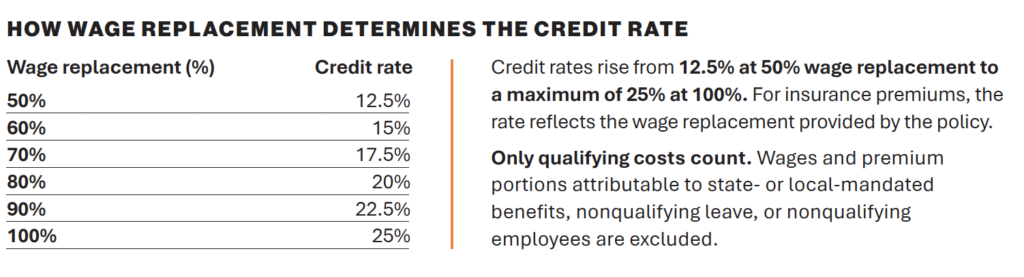
The tables below lay out what changed, which requirements remain unchanged, and how wage replacement determines the credit rate.
_______________________
_______________________
_______________________
More Than a Year-End Tax Calculation
Identifying and substantiating Section 45S credits requires specialist understanding of policy terms, employee eligibility, funding arrangements, and applicable rules.
Maintaining credit readiness is equally demanding: leave activities evolve, eligibility changes, and interdependencies across payroll, carriers, and state programs require ongoing coordination and reconciliation.
_______________________
BeneSphere: Embedded Expertise. End-to-End Execution.
Powered by BENEFITSCAPE, BeneSphere™ provides system-agnostic RegTech for benefits and compliance execution across the end-to-end benefits ecosystem. Its embedded domain intelligence supports Section 45S readiness, execution, and compliance — as a stand-alone RegTech solution or as part of BeneSphere’s wider orchestration of employee benefits delivery.
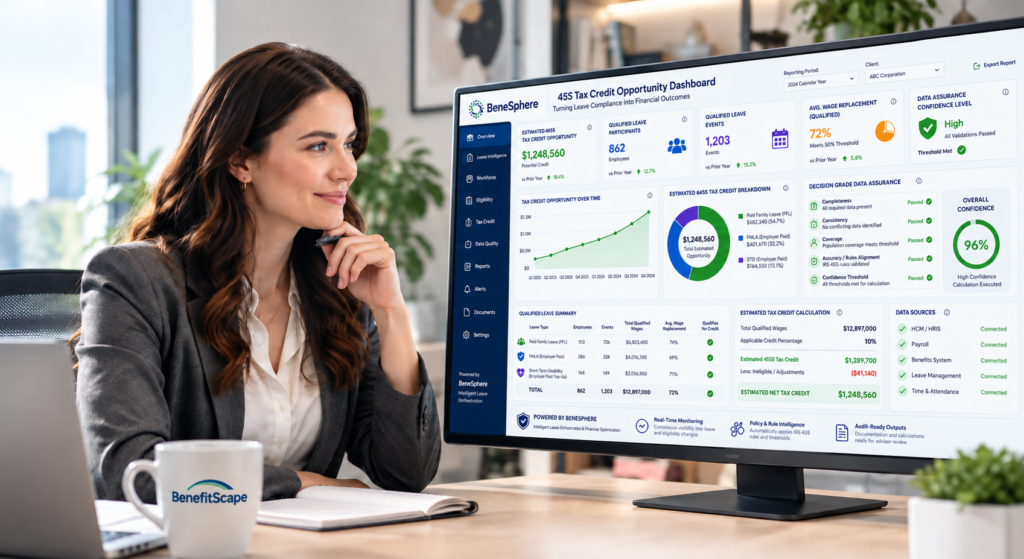
BeneSphere assembles and verifies data for qualified tax advisor assessment, orchestrates ongoing data and workflows, and assembles audit-ready evidence to support credit claims. And a continuous view of potential credit value, any outstanding issues, and audit readiness is provided by a BeneSphere live dashboard.
_______________________
Download a short guide to BeneSphere‘s stand-alone Section 45S solution here. And an overview of the Section 45S changes here.
Request a PFML Credit Review to explore your existing program’s eligibility, potential credit value, and any changes needed to proceed by emailing info@benefitscape.com or calling +1 508-655-3307.
_______________________
Benefits Assurance delivered by BeneSphere™